ISC Class 12 Accounts Important Questions 2027 (Repeated in Board Exams)
Last updated:
98 question patterns that appeared in two or more of the analysed papers (4 board + 4 official sample papers (2023–2026)). The numbers change; the question does not.
Fundamentals of Partnership
1. Prepare P&L Appropriation Account (interest on capital/drawings, salary, commission, partner's loan)
5×Board 2023Board 2026Sample 2023Sample 202410 marks
Julie, Jenny and Sadiq were partners in a firm. On 1st April, 2024, the firm's book showed the following balances:
Particulars | Julie (₹) | Jenny (₹) | Sadiq (₹)
Capital Account | 4,50,000 | 1,50,000 | 2,50,000
Current Account | 50,000 (Cr) | 20,000 (Cr) | 30,000 (Dr)
• On 1st July, 2024, Julie gave a loan of ₹1,00,000 to the firm.
• On 1st October, 2024, the firm took Jenny's premises on rental basis and agreed to pay ₹5,000 per month.
Their Partnership Deed provided the following:
(a) Interest on Capital to be allowed @ 8% per annum.
(b) Interest on Current Account to be allowed / charged @ 10% per annum.
(c) Interest on Drawings to be charged @ 6% per annum.
(d) 10% of the net profit to be transferred to General Reserve.
Jenny withdrew ₹4,000 at the end of each month starting from 30th April, 2024 and Sadiq withdrew ₹4,000 at the beginning of each month starting from 1st October, 2024.
After considering interest on Julie's loan and rent allowed to Jenny, the net profit of the firm for the year ended 31st March, 2025, stood at ₹2,60,000.
You are required to:
(i) Prepare Profit and Loss Appropriation Account for the year ended 31st March, 2025. [7]
(ii) Prepare Julie's Loan Account. [2]
(iii) Record the closing entry for rent allowed to Jenny. [1]
2. Past adjustments: rectify omitted interest, salary, commission or wrong ratio
4×Board 2023Board 2025Board 2026Sample 202510 marks
(A) Baljeet and Jacob are partners sharing profits and losses in 4:1 ratio. On 1st April, 2024, capital balances of Baljeet and Jacob were ₹2,30,000 and ₹3,20,000 respectively.
The net profit for the year 2024-25 of ₹1,20,000 was shared equally by the partners without:
• Allowing Interest on Capital @ 10% per annum.
• Charging Interest on Drawings @ 6% per annum.
During the year, Baljeet withdrew ₹30,000.
You are required to pass the necessary journal entries to rectify the errors made by the firm in distribution of profits. [5]
(B) Karim, Micky and Jai are partners sharing profits and losses in the ratio of 3:2:1. On 1st April, 2024, their capital balances were ₹2,10,000, ₹1,20,000 and ₹1,00,000 respectively.
As per the Partnership Deed,
• Interest on Capital to be allowed @ 10% per annum.
• Salary to be allowed to Karim @ ₹2,000 per month.
• Jai to compensate the deficit in the net profit, if the net profit is less than ₹2,50,000 per annum.
The net profit for the year ended 31st March, 2025 was ₹2,00,000 before allowing Interest on Capital but after allowing Karim's salary.
You are required to:
(i) Prepare Profit and Loss Appropriation Account for the year ended 31st March, 2025. [4]
(ii) Find the balance of Jai's Capital after distribution of profits. [1]
3. Guarantee of profit: P&L Appropriation / rectifying entries
2×Sample 2023Sample 202610 marks
(A) Saoli and Paoli are partners in a firm sharing profits and losses equally. The trading profit for the year ending 31st March, 2025 was ₹51,800. [4]
Other information:
(a) Interest on drawings: Saoli ₹1,200 and Paoli ₹1,000.
(b) Interest on Paoli's loan to the firm, not debited in the Profit & Loss a/c ₹6,000.
(c) Interest on capital: Saoli ₹20,000 and Paoli ₹15,000.
(d) Salary to partners: Saoli ₹15,000 and Paoli ₹10,000.
Prepare Profit & Loss Appropriation account for the year ended 31st March, 2025.
(B) Das, Roy and Sen are partners in a firm. The profit of the firm, for the year ended 31st March, 2025, was ₹1,20,000 which was equally distributed among them, without providing for the following provisions of the partnership deed: [6]
(a) Roy had guaranteed that the firm would earn a profit of at least ₹1,35,000. Any shortfall in these profits would be personally compensated by him.
(b) Profits to be shared in the ratio of 2:2:1.
(c) Sen is guaranteed by the firm that his share of profits, in any given year, would be a minimum of ₹30,000.
You are required to pass the necessary Journal entries to rectify the error in accounting on 1st April 2025.
4. Partner's commission/salary: appropriation, not a charge (1 mark)
2×Board 2026Sample 20251 marks
Assertion: Commission allowed to a partner is debited to Profit and Loss Appropriation Account.
Reason: Commission allowed to a partner is treated as a charge against profit.
Which one of the following is correct?
(a) Both Assertion and Reason are true and Reason is the correct explanation for Assertion.
(b) Both Assertion and Reason are true but Reason is not the correct explanation for Assertion.
(c) Assertion is true and Reason is false.
(d) Both Assertion and Reason are false.
5. Prepare partners' capital accounts after appropriations
2×Board 2024Sample 202610 marks
Raman, Shivam and Namita are partners sharing profits and losses in the ratio of 1:1:2. On 31st March, 2024, their books showed the following balances:
Partners | Capital Account | Current Account | Loan from Partner
Raman | ₹2,00,000 | ₹1,00,000 (Cr) | -
Shivam | ₹4,00,000 | ₹50,000 (Dr.) | ₹1,50,000
Namita | ₹6,00,000 | ₹1,50,000 (Cr) | -
On 1st April, 2024, they adopted the fluctuating capital method of accounting, thereby transferring the current account balances to their capital accounts.
Their partnership deed provided for the following:
• Interest on capital to be allowed @ 10% per annum.
• A monthly allowance of ₹8,000, ₹6,000 and ₹4,000 to be allowed to Raman, Shivam and Namita respectively.
• Interest on loan taken from a partner to be allowed at 10% per annum. Additional Loan was taken from Shivam on 1st October, 2024 amounting to ₹50,000.
During the year ending 31st March, 2025, the firm earned a net profit of ₹5,00,000 before allowing interest on Shivam's loan.
For the year ending 31st March, 2025 you are required to:
(i) Prepare Partners' Capital a/c [6]
(ii) Pass adjusting entry for interest on loan from Shivam. [1]
(iii) Prepare Shivam's loan account. [2]
(iv) Pass Journal entries for transferring the current account balances of Shivam and Namita to their capital accounts. [1]
6. Journal entries for capital changes, interest on capital and profit distribution
2×Board 2024Board 202510 marks
Tim and Leena started a partnership business on 1st July, 2023, with fixed capital contributions of ₹3,00,000 and ₹2,50,000 respectively.
On 1st January, 2024, they decided that the total fixed capital of the firm to be ₹6,00,000 contributed by the partners in the profit-sharing ratio. Accordingly on 1st January, 2024, Tim and Leena introduced or withdrew capital.
Their partnership deed contained the following clauses:
(a) Interest on capital to be allowed @ 10% per annum to both the partners.
(b) Rent @ ₹2,000 per month to Tim for the use of his premises for business purposes.
(c) 10% of the Trading Profit to be transferred to General Reserve.
(d) The profit-sharing ratio of the partners to be 3:2.
The trading profit of the firm for the first year of the partnership after considering all charges against profits was ₹1,50,000.
You are required to pass journal entries for the year 2023-24.
Goodwill
7. Goodwill by super profit method (years' purchase)
4×Board 2023Sample 2023Sample 2024Sample 20253 marks
Kriti and Atif are partners sharing profits and losses equally. On 31st March, 2024, they admitted David as a third partner for 1/5 share in the profits.
It is decided that on David's admission:
• Atif would retain his original share
• Goodwill would be valued by the super profit method on the basis of the following information:
(a) Balance Sheet of Kriti and Atif (an extract) as at 31st March, 2024
Liabilities | Amount (₹) | Assets | Amount (₹)
General Reserve | 25,000 | Current A/c: Atif | 10,000
Capital A/c: Kriti 2,50,000; Atif 1,75,000 | 4,25,000 | |
Current A/c: Kriti | 40,000 | |
(b) The normal rate of return is 12% per annum.
(c) Average profits of the firm for last four years are ₹74,000.
You are required to calculate:
(i) The sacrificing ratio of the partners.
(ii) The value of goodwill of the firm at four years' purchase of the super profit.
8. Capitalisation method: find normal rate of return / components (1 mark)
3×Board 2026Sample 2025Sample 20261 marks
On the date of Sahil's retirement as a partner from a firm, Goodwill was valued at ₹1,25,000 under Capitalisation of Super Profit method. Super Profit of the firm was ₹15,000.
Find the Normal Rate of Return that was used to ascertain the Goodwill of the firm.
9. Goodwill by average / weighted average profit method
3×Board 2024Board 2025Board 20263 marks
Rani and Mani are partners in a firm sharing profits and losses in 3:2 ratio. On 1st April, 2025 they admit Jasmine as a partner. Rani sacrifices 1/3rd of her share and Mani sacrifices 1/2 of his share. As per the provisions of the Partnership Deed, Goodwill is to be valued on the basis of two years' purchase of previous three years' weighted average profit.
Weights applicable as 1, 2 and 3 for the years 2022-23, 2023-24 and 2024-25 respectively. Profits for the previous three years are as follows:
Year | Profit (₹)
2022-23 | 56,000
2023-24 | 72,000
2024-25 | 85,000
During the year 2023-24, closing stock was undervalued by ₹5,000.
On the date of Jasmine's admission, you are required to:
(i) Calculate firm's Goodwill. [2]
(ii) Calculate the new profit-sharing ratio of Rani, Mani and Jasmine. [1]
10. Nature and features of goodwill (1 mark)
2×Sample 2023Sample 20241 marks
Assertion: Goodwill is a fictitious asset.
Reason: Goodwill has a realisable value.
Which one of the following is correct?
(a) Both Assertion and Reason are correct, and Reason is the correct explanation for Assertion.
(b) Both Assertion and Reason are correct, but Reason is not the correct explanation for Assertion.
(c) Assertion is false and Reason is true.
(d) Assertion is true and Reason is false.
11. Average profit method: formula and normal-profit adjustments (1 mark)
2×Board 2023Board 20251 marks
To value the goodwill of a partnership firm at the time of its reconstitution, which one of the following items is added back to the previous year's profit to find the normal profit?
(a) Gain from sale of shares
(b) Insurance premium paid
(c) Undervaluation of closing stock
(d) Overvaluation of closing stock
Admission of a Partner
12. Prepare partners' capital accounts on admission (goodwill premium, revaluation, capital adjustment)
5×Board 2023Board 2024Board 2026Sample 2023Sample 20256 marks
Ravi and Prakash are partners sharing profits and losses in the ratio of 3:7. The Balance Sheet of Ravi and Prakash as at 31st March, 2025 is given below:
Balance Sheet of Ravi and Prakash as at 31st March 2025
Liabilities | ₹ | Assets | ₹
Ravi's Capital | 65,000 | Goodwill | 10,000
Prakash's Capital | 35,000 | Land & Building | 60,000
Workmen Compensation Reserve | 20,000 | Office Equipment | 50,000
Bills Payable | 15,000 | Debtors | 24,000
Bank Overdraft | 25,000 | Bills Receivable | 16,000
Total | 1,60,000 | Total | 1,60,000
On 1st April, 2025, they admit Nasir for 1/4th share of profits on the following terms:
(a) Nasir to bring ₹50,000 as his capital and the necessary amount as his share of goodwill.
(b) Firm's Goodwill to be valued at ₹1,20,000.
(c) Liability for Workmen Compensation to be recorded as ₹15,000.
(d) Capital Accounts of Ravi and Prakash to be adjusted based on Nasir's capital and his share of profit. Any deficit or surplus in their capital to be adjusted by opening Current Account.
You are required to:
(i) Prepare Partners' Capital Account. [5]
(ii) Calculate the balance of Cash at bank on the date of Nasir's admission. [1]
13. Journal entries on admission (premium for goodwill in cash, kind or through current account)
4×Board 2023Board 2026Sample 2024Sample 20266 marks
Ishita and Divya are partners in a firm sharing profits and losses in the ratio of 5:3. Their Balance Sheet as at 31st March, 2025, is as follows:
Balance Sheet of Ishita and Divya as at 31st March, 2025
Liabilities | ₹ | Assets | ₹
Ishita's Capital | 5,10,000 | Freehold Premises | 2,50,000
Divya's Capital | 2,00,000 | Plant | 2,80,000
General Reserve | 90,000 | Debtors | 1,50,000
Creditors | 80,000 | Closing Stock | 1,40,000
| | Divya's Current A/c | 25,000
| | Cash at Bank | 35,000
Total | 8,80,000 | Total | 8,80,000
On 1st April, 2025, they admit Abhinav as a new partner on the following terms:
(a) New profit-sharing ratio of Ishita, Divya and Abhinav to be 3:4:1.
(b) Divya's Current Account to be transferred to her Capital Account.
(c) 4% of the Debtors to be maintained as Provision for doubtful debts.
(d) Creditors of ₹20,000 are not to be paid, as they are untraceable.
(e) Abhinav to contribute ₹2,70,000 as his capital and ₹40,000 as his share of Goodwill.
You are required to do the following on the date of Abhinav's admission:
(i) Record the necessary journal entries in the books of the reconstituted firm. [5]
(ii) Calculate firm's Goodwill. [1]
14. New partner's capital based on adjusted capitals (1 mark)
3×Board 2024Sample 2025Sample 20261 marks
Rahul and Nikhil are partners in a firm. They admit Tanvi for 1/5th share. On the date of her admission, the firm's book shows the following balances:
Rahul's Capital: ₹2,80,000
Nikhil's Capital: ₹2,20,000
Tanvi contributes 20% of the adjusted capital of Rahul and Nikhil. She also contributes ₹20,000 as half of her share of goodwill.
Pass the journal entry to record the capital contribution made by Tanvi.
15. Hidden goodwill from new partner's capital + capital accounts
3×Sample 2023Sample 2024Sample 20266 marks
Anu and Binu were partners sharing profits and losses in the ratio of 4:1. Their Balance sheet as at 31st March, 2025 was as follows:
Balance sheet of Anu and Binu as at 31st March 2025
Liabilities | ₹ | Assets | ₹
Capital Accounts: Anu 25,000; Binu 10,000 | 35,000 | Bank | 26,000
General Reserve | 10,000 | Building | 49,000
Bills Payable | 40,000 | Goodwill | 1,000
| | Debtors | 9,000
Total | 85,000 | Total | 85,000
On 1st April 2025, Tinu is admitted as a new partner on the following terms:
(a) New profit-sharing ratio of the partners to be 2:1:1.
(b) Tinu shall bring in ₹16,000 as his capital and the required amount of Goodwill in cash.
(c) Bills payable was overvalued by ₹2,000.
(d) The value of Goodwill of the firm to be calculated on the basis of Tinu's share in profit and the capital contributed by him.
(e) Provision for bad and doubtful debts ₹1,000 to be created out of General Reserve.
Pass the journal entries for treatment of Goodwill and prepare Capital accounts of all the partners.
16. Value of revalued assets on admission (furniture reduced by / to %)
3×Board 2026Sample 2023Sample 20241 marks
Rishabh and Alex are partners in a firm sharing profits and losses in the ratio of 3:2. At the time of Manpreet's admission, the value of Motor Vehicle in the firm's Balance Sheet was ₹1,50,000. While doing the re-assessment, it was found overvalued by 25%.
Calculate the value of Motor Vehicle to be shown in the Balance Sheet of the reconstituted firm.
(a) ₹1,12,500
(b) ₹1,20,000
(c) ₹1,87,500
(d) ₹2,00,000
17. Net effect of revaluation adjustments on admission (1 mark)
2×Board 2023Sample 20251 marks
Aman and Vinod are partners in a firm. Their Balance Sheet showed:
Gross Debtors: ₹1,52,000
Provision for doubtful debts: ₹1,000
On Milin's admission as a new partner, the assets and liabilities are to be revalued as:
• Unaccounted accrued income of ₹10,000 to be provided for
• Bills Payable of ₹10,000 which were recorded, to be discharged at a rebate of 10%
• Debtors of ₹2,000 to be irrecoverable
• Provision for doubtful debts to be provided @ 2% of the debtors
What is the net effect of revaluation of assets and liabilities?
18. Treatment of reserves, workmen compensation and accumulated losses on admission
2×Board 2024Board 20253/6 marks
Ajay and Bijoy are two partners sharing profits and losses in the ratio of 2:1.
Balance Sheet of Ajay and Bijoy (extract) as at 31st March, 2024
Liabilities | ₹ | Assets | ₹
Workmen Compensation Reserve | 1,200 | |
Additional information:
(a) On 1st April, 2024, they admitted Sujay as a partner with 1/4 share in the profits.
(b) The Workmen Compensation Reserve to be reduced to ₹900 in the reconstituted firm.
You are required to give the accounting treatment of Workmen Compensation Reserve on the date of Sujay's admission.
Retirement and Death of a Partner
19. Journal entries for paying the retiring partner (by asset, bill or bank loan)
3×Sample 2023Sample 2024Sample 20253 marks
Mita, Sita and Rita are partners in a firm. Rita retires from the firm on 31st March, 2024. Her claim, including her capital and her share of goodwill, is determined at ₹2,50,000. On this date the firm's books showed:
(a) An unrecorded investment valued at ₹60,000 which was given to an unrecorded creditor of ₹1,16,000 in settlement of his claim of ₹70,000.
(b) An unrecorded vehicle which was given to Rita at the market value of ₹46,000 in part settlement of her claim.
The balance of Rita's claim was discharged by cheque.
You are required to pass journal entries to record the above transactions in the books of the firm on 31st March, 2024.
20. Continuing partners bring cash to pay outgoing partner / readjust capitals
3×Board 2023Board 2025Sample 20253/6 marks
Ravi, Ali and Siya are partners in a firm sharing profits and losses in the ratio of 4:3:2. Ali retired from the firm on 31st March, 2024, when the capitals of the partners before the following necessary adjustments stood at:
Ravi ₹23,000
Ali ₹12,000
Siya ₹9,000
Adjustments:
(a) The firm's goodwill to be valued at ₹21,600.
(b) Loss on revaluation of assets and liabilities to be ₹2,700.
On the date of Ali's retirement, the firm had: General Reserve of ₹6,300; Cash & Bank Balance of ₹18,600.
It was decided that Ali be paid through cash brought in by Ravi and Siya in such a manner so as to make their capitals proportionate to their new profit-sharing ratio and a minimum Cash & Bank Balance of ₹10,000 to be maintained in the reconstituted firm.
You are required to pass journal entries to record the above transactions.
21. Reserves on retirement kept in books: single adjusting entry
2×Board 2026Sample 20261/3 marks
Meena, Ricky and Vicky were partners in a firm sharing profits and losses in the ratio of 6:3:1. On 31st March, 2025, Meena retired from the firm and the continuing partners decided to share profits and losses in the ratio of 3:2.
On the date of Meena's retirement, the firm's Balance Sheet showed the following items:
Balance Sheet of Meena, Ricky and Vicky (An extract) as at 31st March, 2025
Liabilities | ₹ | Assets | ₹
General Reserve | 1,80,000 | Investments (Market Value ₹40,000) | 50,000
Investment Fluctuation Fund | 30,000 | |
The continuing partners decided to record the effect of the above items without disturbing the book value of the General Reserve.
You are required to record the necessary journal entries to show the above adjustments.
22. Deceased partner's capital account (interest, drawings, interim profit, goodwill)
3×Board 2023Board 2025Board 20263/6 marks
Kamal, Anwar and Sam were equal partners in a firm. On 1st April, 2025, Sam's capital stood at ₹1,05,000 in the books of the firm.
On 31st July, 2025, Sam died. As per the provisions of the Partnership Deed, Interest on Capital was allowed @ 10% per annum and Interest on Drawings was charged @ 6% per annum.
Till his death, Sam had withdrawn ₹20,000. His interim profit amounted to ₹12,000 and the firm's Goodwill was valued at ₹90,000.
You are required to prepare Sam's Capital Account.
23. Deceased partner's share of profit till death (turnover/time basis)
2×Sample 2023Sample 20263 marks
Amit, Karan and Rakhi were partners in a firm sharing profits and losses in the ratio of 2:2:1. Amit died on 30th June 2024 while the firm closed its books on 31st March. According to their partnership deed, Amit's representative would be entitled to get a share in the interim profits of the firm calculated on the basis of turnover. Turnover and profit for the year 2023-24 were ₹3,00,000 and ₹90,000 respectively and turnover in the year 2024-25 till the date of his death amounted to ₹60,000.
You are required to:
(i) Calculate Amit's share of interim profit. [1]
(ii) Pass the necessary Journal entry showing Amit's share of interim profit. [2]
24. New profit-sharing ratio of continuing partners (1 mark)
2×Board 2026Sample 20241 marks
Malti, Bhumi and Salim were partners sharing profits and losses in the ratio of 3:3:4. Malti died on 31st December 2024. Following entry was passed for the adjustment of interim profit of Malti:
31.12.2024 | Bhumi's Capital A/c Dr. 20,000 | Salim's Capital A/c Dr. 20,000 | To Malti's Capital A/c 40,000 | (Being adjustment entry made for interim profit)
What will be the new profit-sharing ratio for the continuing partners?
(a) 1:1
(b) 3:4
(c) 4:5
(d) 9:11
25. Retiring partner's loan account paid in instalments
2×Board 2024Sample 20243 marks
Kamal, Ali and John are partners in a firm. On Kamal's retirement from the firm on 30th June, 2023, his capital account stood at ₹40,000 after all adjustments.
The partners decided that Kamal be paid 50% of the amount due to him immediately and the balance, along with interest @ 6% per annum, be paid on 30th June, 2024.
The firm closes its books on 31st March every year.
You are required to prepare Kamal's Loan Account till it is finally closed.
26. Revaluation entries on retirement (1 mark)
2×Board 2023Sample 20231 marks
Nikhil, Akhil and Amber are partners in a firm. At the time of Akhil's retirement, Amber takes over furniture of ₹12,000 at ₹10,000.
Choose the correct journal entry from the following options to record this adjustment.
(a) Debit Furniture Account ₹10,000; Credit Amber's Capital Account ₹10,000
(b) Debit Furniture Account ₹12,000; Credit Amber's Capital Account ₹10,000; Credit Revaluation Account ₹2,000
(c) Debit Amber's Capital Account ₹10,000; Credit Furniture Account ₹10,000
(d) Debit Amber's Capital Account ₹10,000; Debit Revaluation Account ₹2,000; Credit Furniture Account ₹12,000
Dissolution of a Partnership Firm
27. Prepare Realisation Account
5×Board 2023Board 2026Sample 2023Sample 2024Sample 20266 marks
Sameer and Daulat were partners sharing profits and losses in the ratio of 2:3. They decided to dissolve the firm on 31st March, 2025. Their Balance Sheet was as under:
Balance Sheet of Sameer and Daulat as at 31st March 2025
Liabilities | ₹ | Assets | ₹
Sameer's Capital | 4,50,000 | Land & Building | 3,20,000
Daulat's Capital | 3,00,000 | Investments | 1,80,000
Trade Creditors | 60,000 | Trade Debtors 70,000 less Provision for doubtful debts 5,000 | 65,000
Sameer's Loan | 50,000 | Closing Stock | 45,000
| | Cash at Bank | 2,50,000
Total | 8,60,000 | Total | 8,60,000
Additional information: The firm was dissolved subject to the following adjustments:
(a) Sameer took over closing stock for the settlement of his loan.
(b) Debtors of ₹15,000 proved bad.
(c) Land & Building was realised at 25% above the book value.
(d) Sameer paid realisation expenses of ₹15,000.
You are required to prepare the Realisation Account.
28. Settle partner's loan on dissolution (journal entry)
3×Board 2023Sample 2024Sample 20261 marks
Priya was a partner in a firm. On the date its dissolution, her loan was appearing on the liability side of the Balance Sheet at ₹25,000. Priya accepted an unrecorded asset of ₹17,500 and the balance was paid to her in cash.
Give the Journal entry for the above transaction.
29. Treatment of items in Realisation Account (1 mark)
3×Board 2026Sample 2023Sample 20251 marks
At the time of dissolution, a firm did not provide any information regarding realisation of the following assets:
P Freehold Premises
Q Office Equipment
R Goodwill
S Furniture
Choose the assets to be realised at the book value of the firm.
(a) P, Q, R
(b) P, Q, S
(c) P, R, S
(d) Q, R, S
30. Order of payment on dissolution (Section 48)
3×Board 2024Sample 2023Sample 20261 marks
On dissolution of a firm, one of the partners, Abhi demands that his loan of ₹1,50,000 be paid before payment of capitals of the partners, whereas other partners, Bobby and Cathy demand that capitals should be paid before the payment of Abhi's loan.
State the correct order of payment. Give a reason for your answer.
31. Calculate amount realised / paid on dissolution (1 mark)
3×Board 2025Board 2026Sample 20241 marks
At the time of dissolution of a firm, Furniture appeared at ₹4,50,000 in the firm's Balance Sheet. One of the creditors to whom an amount of ₹4,00,000 was due, agreed to take over the Furniture at 20% less than the book value and the remaining amount by cheque.
Calculate the amount to be paid to the creditor by cheque.
32. Realisation expenses / partner's remuneration on dissolution (1 mark)
2×Board 2023Sample 20251 marks
Ira (a partner in a firm) was allowed to retain the whole of the stock as her remuneration for services rendered by her in the course of dissolution of the firm. The value of stock was ₹10,000 which had been transferred to the Realisation Account.
Complying with the accounting principle of full disclosure, record the above transaction in the books of the partnership firm at the time of its dissolution.
33. Journal entry for an asset or fictitious item on dissolution (1 mark)
2×Board 2024Board 20251 marks
At the time of the dissolution of the partnership firm of Sanjay and Mitali, its Balance Sheet showed Deferred Revenue Expenditure of ₹30,000.
Give the journal entry to treat this item.
34. Partners' capital accounts and bank account on dissolution
2×Board 2024Board 20256 marks
Mihir and Farhan were partners in a firm sharing profits and losses equally. They dissolved their partnership firm on 31st March, 2024.
On this date, the Balance Sheet of their firm, apart from the realisable assets and outside liabilities, showed the following:
Particulars | ₹
Mihir's Capital | 60,000 (Cr)
Farhan's Capital | 20,000 (Dr)
Workmen Compensation Reserve | 12,000
Profit & Loss Account | 6,000 (Cr)
Bank Account | '?'
On the date of dissolution:
(a) The firm, upon realisation of assets and settlement of liabilities, suffered a loss of ₹10,000.
(b) The amount paid to settle the liabilities exceeded the amount realised from the sale of the assets by ₹8,000.
(c) Stock worth ₹3,000 was taken over by Farhan.
(d) Mihir discharged the Bills Payable, recorded in the books at ₹5,000, at a rebate of ₹100.
(e) There was a workmen compensation claim of ₹4,000.
You are required to prepare on the date of dissolution of the firm:
(i) The Partners' Capital Accounts.
(ii) The Bank Account to determine its balance at bank as shown in the Balance Sheet as at 31st March, 2024, represented by '?'.
Issue of Shares
35. Complete missing figures in share-issue journal / ledger extracts
5×Board 2024Board 2025Sample 2024Sample 2025Sample 202610 marks
Maconie Ltd. issued 50,000 Equity Shares of ₹10 each at ₹15, payable as follows:
(a) On Application, ₹6 including premium of ₹2
(b) On Allotment, ₹5 including balance of premium
(c) Remaining amount on First and Final call after 3 months of shares being allotted
Applications were oversubscribed. Applications for 5,000 shares were rejected and money refunded immediately, and the remaining applications were allotted on pro rata basis in the ratio of 7:5.
Journal of Maconie Ltd.
1. Bank A/c Dr. ? | To Share Application A/c ? (Being application money received)
2. Share Application A/c Dr. ---- | To Share Capital A/c ? | To Securities Premium A/c 1,00,000 | To Bank A/c 30,000 | To Share Allotment A/c ? (Being application money transferred and adjusted)
3. Share Allotment A/c Dr. 2,50,000 | To Share Capital A/c 1,00,000 | To Securities Premium A/c 1,50,000 (Being allotment money due)
4. Bank A/c Dr. ? | To Share Allotment A/c ? | To Calls in advance A/c 8,000 (Being allotment money received including amount received for call)
5. Share First & Final Call A/c Dr. 2,00,000 | To Share Capital A/c 2,00,000 (Being first call money due)
6. Bank A/c Dr. 1,92,000 | Calls in advance A/c Dr. 8,000 | To Share First & Final Call A/c 2,00,000 (Being share first & final call money received)
7. Interest on calls in advance A/c Dr. ? | To Shareholders' A/c ? (Being interest due on calls in advance as per provisions of Table F of Schedule I of the Company Act, 2013)
You are required to:
(i) Complete the entries no. 1, 2, 4 and 7 along with the missing information represented by '?'. [8]
(ii) Pass journal entries to pay and close Interest on Calls-in-Advance Account. [2]
36. Maximum discount on reissue of forfeited shares (1 mark)
4×Board 2026Sample 2023Sample 2025Sample 20261 marks
Ravi is a shareholder at Sarang Ltd., holding 5,000 shares of ₹20 each. He paid only application money of ₹5 including premium of ₹1. His shares were forfeited after the Final Call was made.
The maximum discount per share that can be offered by Sarang Ltd. to re-issue the forfeited shares is:
(a) ₹1
(b) ₹4
(c) ₹5
(d) ₹15
37. Journal entries: share issue, forfeiture and reissue
5×Board 2023Board 2025Board 2026Sample 202310 marks
Sara Ltd. registered with 5,00,000 Equity Shares of ₹10 each. The company offered 1,00,000 Equity Shares to the public for subscription at 50% premium, payable as:
On Application ₹5
On Allotment ₹7 (including premium)
On First and Final Call ₹3
Applications were received for 1,50,000 shares. The company rejected the applications for 10,000 shares and refunded the amount immediately to the applicants. The remaining applications were allotted on pro-rata basis.
A shareholder, who had applied for 7,000 shares, failed to pay allotment and call money. His shares were forfeited by the company after First and Final Call. Half of the forfeited shares were re-issued at a discount of 20% as fully paid up.
You are required to pass the necessary journal entries in the books of Sara Ltd.
38. Pro-rata allotment with excess application money adjusted (named applicants)
3×Board 2023Sample 2024Sample 202510 marks
Hero Ltd. was registered with a capital of ₹5,00,000 divided into 20,000 shares of ₹25 each, payable as:
On Application ₹5 per share
On Allotment ₹10 per share
On Call The Balance
The company offered to the public for subscription 10,000 shares. It received applications for 11,100 shares.
From amongst the applicants:
(i) Vimal, who had applied for 1,200 shares, paid ₹6,000 on application, but was allotted only 600 shares.
(ii) Mohan applied for 1,000 shares, paid the full amount of ₹25,000 with his application but was allotted only 500 shares.
(iii) Vineet, who had applied for 1,500 shares, paid his application and allotment money in order but did not pay the call money.
(iv) The remaining applicants paid as and when due.
The surplus money paid by both Vimal and Mohan was used towards allotment and call and any surplus beyond the call was refunded.
The company forfeited Vineet's shares and later re-issued 500 of the forfeited shares @ ₹20 per share fully paid up.
You are required to pass journal entries in the books of Hero Ltd.
39. Subscribed capital / share capital terms (1 mark)
2×Board 2024Sample 20241 marks
Tulip Ltd. allotted 45,000 Equity shares of ₹10 each to the public. The first and final call of ₹2 per share was not received on 1,000 shares, which were forfeited by the company. Later, 600 of the forfeited shares were reissued at ₹7 fully paid up.
What is the Subscribed Capital of the company?
(a) ₹4,49,200
(b) ₹4,50,000
(c) ₹4,40,000
(d) ₹4,46,000
40. Calls in advance / calls in arrears with interest (Table F)
2×Board 2024Board 202610 marks
Skyline Ltd. invited applications for 20,000 shares of ₹10 each, payable as:
On 1st June, 2024 ₹3 on Application
On 1st July, 2024 ₹2 on Allotment
On 1st September, 2024 ₹2 on First Call
On 1st December, 2024 ₹3 on Second and Final Call
Shares were fully subscribed.
Vikram, a shareholder holding 2,000 shares, paid the entire money with the allotment.
As per the Articles of Association, Interest on Calls-in-Advance was allowed @ 12% per annum.
You are required to do the following during the year 2024-25:
(i) Pass the necessary journal entries in the books of Skyline Ltd. to record Interest on Calls-in-Advance. [3]
(ii) Prepare Share Capital Account. [4]
(iii) Prepare Calls-in-Advance Account. [3]
41. Pro-rata allotment / oversubscription options (1 mark)
2×Board 2023Board 20251 marks
Read the following news item regarding issue of shares by TVS Supply Chain and answer the question that follows:
'TVS Supply Chain IPO subscribed 2.8 times' (Source: The Hindu, Business Line, 15 August, 2023)
Which of the following options can TVS Supply Chain avail to deal with its over-subscribed shares?
P Reject all the over-subscribed shares and refund the excess application money.
Q Allot all shares applied for on a pro-rata basis.
R Allot all shares applied for.
S Allot in full to some applicants, allot shares on a pro-rata basis to a few applicants and refund the application money to some applicants.
(a) P, Q and R
(b) Q, R and S
(c) P, R and S
(d) P, Q and S
Issue of Debentures
42. Debentures issued for consideration other than cash (vendor, promoters, underwriters)
4×Board 2023Board 2026Sample 2025Sample 20263 marks
During the year 2024-25, IP Ltd. issued:
• 10,000, 7% Debentures of ₹50 each at a discount of 5% to the Promoters of the company.
• 2,000, 7% Debentures of ₹50 each at par to BL & Co. for the settlement of their underwriting commission.
You are required to record the necessary journal entries in the books of IP Ltd. for the issue of debentures. (Ignore writing off capital losses and interest on debentures)
43. Writing off loss on issue of debentures (1 mark)
4×Board 2024Board 2026Sample 2024Sample 20251 marks
Bisco Ltd. issued 10,000, 9% Debentures of ₹100 each at a discount of 4%, redeemable at a premium of 8% after five years. The company had a balance of ₹80,000 in Securities Premium Account and ₹1,00,000 in Statement of Profit and Loss.
Give the journal entry to write off the Loss on issue of Debentures.
44. Interest on debentures incl. collateral debentures (1 mark)
4×Board 2023Sample 2025Sample 20261 marks
On 1st April 2023, Anand Limited issued 10%, 50,000 Debentures of ₹100 each as collateral security to ABC Bank against a loan raised of ₹80,00,000. It also issued 12%, 40,000 Debentures of ₹100 each on 1st October, 2023 in the stock market to invest money in a new line of product.
How much interest on Debentures become payable by the company on 31st March 2024?
(a) ₹7,40,000
(b) ₹2,40,000
(c) ₹5,00,000
(d) ₹4,80,000
45. Debentures payable in instalments: calls in advance / arrears
3×Board 2025Sample 20253 marks
On 1st April, 2023, Vishesh Co. Ltd made an issue, which was fully subscribed, of 8,000, 5% Debentures of ₹100 each at a premium of 10% repayable at par at the end of 10 years. The debentures were allotted on 31st August, 2023, subscriptions being payable:
10% with Application
50% (along with premium) on Allotment
20% with First Call
Balance on the Second & Final Call
One debenture holder holding 200 debentures paid the First Call with Allotment.
You are required to prepare the Cash Book for the year 2023-24 to record the above issue of debentures. (Ignore interest on debentures).
46. Loss on Issue of Debentures A/c and Securities Premium A/c
2×Board 2024Sample 20263 marks
On 1st April, 2024, Zubin Ltd. issued 3,000, 8% Debentures of ₹100 each at a discount of 5% to be redeemed after two years at a premium of 6%.
On 31st March, 2025, Zubin Ltd. had the following balances in its books before adjustments of capital losses:
Securities Premium ₹23,000
Statement of Profit/Loss ₹18,000
General Reserve ₹20,000
The company writes off all its capital losses in the same year.
You are required to prepare the following for the year 2024-2025:
(i) Loss on Issue of Debentures A/c [2]
(ii) Securities Premium A/c [1]
47. Journal entries for issue of debentures (discount / premium, redeemable at premium)
2×Board 2026Sample 20233 marks
On 1st July, 2024, Udaan Ltd. issued 20,000, 7% Debentures of ₹100 each at a premium of 5%, redeemable after 5 years at a premium of 10%. According to the terms of issue of debentures, interest on debentures was payable yearly on 31st March.
You are required to:
(i) Pass necessary journal entries in the books of Udaan Ltd. on the date of issue of debentures. [2]
(ii) Prepare Interest on Debentures Account for the year 2024-25. [1]
48. Premium on redemption vs securities premium (1 mark)
2×Board 2025Sample 20231 marks
Premium on Redemption of Debentures is debited to:
(a) Debentures Account
(b) Loss on issue of Debentures Account
(c) Debenture holders' Account
(d) Debenture Application and Allotment Account
Redemption of Debentures
49. Prepare ledger accounts on redemption (DRR, DRI, Debentureholders)
7×Board 2024Board 2025Sample 2023Sample 2024Sample 2025Sample 20263 marks
APL Ltd., an unlisted construction company has 50,000, 10% Debentures of ₹100 each due for redemption at par on 31st March, 2024. The Debenture Redemption Investment was purchased on 30th April, 2023 and was sold on the date of redemption at 104% less 0.7% commission. APL Ltd. had sufficient balance in its Debenture Redemption Reserve A/c as per the provisions of the Companies' Act, 2013.
You are required to prepare the following Ledger Accounts for the year 2023-2024:
(i) Debenture Redemption Reserve A/c [1]
(ii) Debenture Redemption Investment A/c [2]
50. Debenture Redemption Reserve rules (1 mark)
5×Board 2023Board 2024Board 2025Sample 20241 marks
Why is it advisable for an unlisted manufacturing company to start transferring its profits to Debenture Redemption Reserve from the year of the issue of its non-convertible debentures?
51. Journal entries for redemption of debentures with DRI
5×Board 2023Board 2024Board 2026Sample 20243 marks
On 1st April, 2022, RR Ltd., a listed manufacturing company issued 15,000, 8% Debentures of ₹100 each, due for redemption on 31st March, 2025 at a premium of 10%. The issue was fully subscribed. The debentures were redeemed on the due date. On 1st April, 2024, the company invested the required amount in the Debenture Redemption Investment Account, earning an interest @ 6% per annum.
You are required to pass necessary journal entries in the books of RR Ltd. for the redemption of debentures for the year 2024-25. (Ignore Interest on Debentures)
52. Debenture Redemption Investment (15%): amount / date (1 mark)
3×Board 2026Sample 20231 marks
Karma Ltd., an unlisted manufacturing company, had 30,000, 9% Debentures of ₹100 each due for redemption on 31st March, 2025.
Calculate the amount to be invested in Debenture Redemption Investment Account for the redemption of Debentures, as per the provisions of the Companies' Act, 2013.
Final Accounts of Companies
53. Heading and sub-heading of an item in company Balance Sheet (1 mark)
6×Board 2023Board 2024Board 2025Board 2026Sample 2023Sample 20251 marks
'Mindspace Business Parks REIT acquires three office assets from sponsor K Raheja Corp for ₹2916 crores.' (Source: www.livemint.com, 28 Nov, 2025)
Mention the heading and the sub-heading under which office assets of Mindspace Business Parks REIT will be shown in the Balance Sheet as per Schedule III of the Companies' Act, 2013.
54. Show items in notes to accounts (reserves, borrowings, other items)
3×Board 2025Sample 2024Sample 20256 marks
Hoody Ltd. made the following borrowings in the year 2023-24:
On 1st April, 2023: Ten year, 10% Bank Loan from AZ Bank secured by a primary security and 20,000, 6% Debentures of ₹100 each as collateral security, the issue of which was recorded in the books. | ₹25,00,000
On 1st October, 2023: 5,000, 8% Debentures of ₹100 each, redeemable at par in five equal annual instalments. | ₹5,00,000
The terms of the borrowings were:
• The redemption of 8% Debentures to begin from 30th September, 2024.
• Interest on Bank Loan and Debentures to be paid annually.
Additional information: In the year 2023-24, the company defaulted on the payment of the interest on bank loan.
You are required to show the above items in Notes to Accounts accompanying the Balance Sheet of Hoody Ltd. prepared as per Schedule III of the Companies Act, 2013, as at 31st March, 2024.
55. Equity and Liabilities extract of company Balance Sheet
2×Sample 2023Sample 20266 marks
On 31st March 2025, Rishiraj Ltd., an unlisted construction company, showed the following balances:
Particulars | Amount (₹)
Equity Share Capital of ₹10 each | 10,00,000
Calls-in-arrear (₹2 per share) | 30,000
8% Debenture of ₹100 each | 4,00,000
6% Bank Loan | 2,10,000
Bank Overdraft | 54,000
Cash Credit | 12,000
Debenture Redemption Reserve | 40,000
Premium on redemption of debentures | 20,000
Interest on 8% Debentures due on 31.3.2025 has not been paid | 32,000
You are required to prepare an extract of Balance Sheet as at 31st March, 2025, showing the Equity and Liabilities. (Ignore Notes to Accounts)
56. Share capital note to accounts (+ related Balance Sheet amounts)
3×Board 2023Board 2024Board 20266 marks
On 31st March 2025, BIMA Ltd., showed the following balances:
Particulars | ₹
Equity Share Capital of ₹10 each, called up to ₹6 | 30,00,000
Calls-in-Arrears | 40,000
6% Debentures | 10,00,000
8% Bank Loan | 5,00,000
Securities Premium | 70,000
Calls-in-Advance | 40,000
Statement of Profit & Loss (Dr) | 50,000
Interest on debentures accrued but not due | 15,000
Additional information:
• BIMA Ltd. incorporated with an authorised capital of 8,00,000 Equity Shares of ₹10 each, of which 5,00,000 shares were issued to the public. Shares were subscribed in full.
• 8% Bank loan was taken on 1st April 2022, due for repayment on 31st August, 2025.
You are required to:
(i) Prepare Notes to Accounts showing Share Capital. [2]
(ii) Give the amount for each of the following: (a) Reserve and Surplus [1] (b) Long term borrowings [1] (c) Short term borrowings [1] (d) Other Current liabilities [1]
Financial Statement Analysis
57. Prepare common size Balance Sheet
4×Board 2026Sample 2023Sample 2025Sample 20263 marks
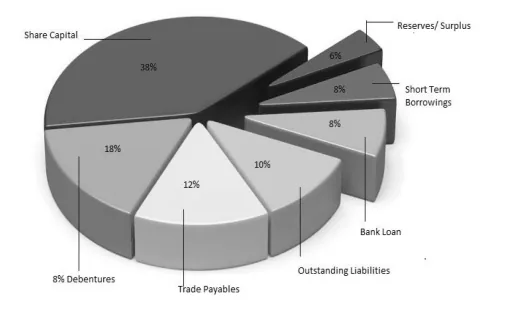
The pie chart below shows the Equity and Liabilities of Moonside Ltd. as at 31st March, 2025 (as read from the chart: Share Capital 38%, Reserves/Surplus 6%, Short Term Borrowings 8%, Bank Loan 8%, Outstanding Liabilities 10%, Trade Payables 12%, 8% Debentures 18%).
You are required to prepare the Equity and Liability side of Common Size Statement of Moonside Ltd. as at 31st March, 2025, when the total of the Equity and Liabilities side is ₹10,00,000.
58. Calculate percentage change (1 mark)
4×Board 2025Board 2026Sample 2025Sample 20261 marks
Silver prices scaled a new peak of ₹1,73,000 per kg on Monday after an unprecedented single-day gain of ₹11,000 per kg driven by increasing demand from investors amid a global shortage of the precious metal. (Source (edited): www.economictimes.indiatimes.com, 13 Oct, 2025)
Calculate the percentage change (up to two decimal places) in prices of silver.
59. Prepare / complete comparative statement
3×Board 2023Board 2024Board 20253 marks
Following are the particulars of Richmond Ltd.:
Particulars | 31.03.2024 (₹) | 31.03.2023 (₹)
Revenue from Operations | 5,00,000 | 4,00,000
Purchases of stock-in-trade | 3,00,000 | 3,60,000
Opening inventory of stock-in-trade | 1,40,000 | 1,00,000
Adjusted purchases of stock-in-trade | 4,10,000 | 3,20,000
You are required to calculate the absolute change and percentage change of the following items at the end of the year 2023-24 vis-a-vis the closing amounts of the year 2022-23:
(i) Revenue from operations
(ii) Purchases of stock in trade
(iii) Closing inventory of stock-in-trade
Cash Flow Statement
60. Classify a transaction as operating / investing / financing (1 mark)
9×Board 2023Board 2024Board 2025Board 2026Sample 2023Sample 2024Sample 2025Sample 20261 marks
Bank overdraft of Asha Ltd. on 31st March, 2024 and 31st March, 2025 were ₹30,000 and ₹36,000 respectively.
How will the change in Bank overdraft be shown in the Cash Flow Statement of Asha Ltd. for the year ended 31st March, 2025?
(a) Add to Financing Activities
(b) Add to Operating Activities
(c) Less from Operating Activities
(d) Less from Financing Activities
61. Prepare Cash Flow Statement from two Balance Sheets
7×Board 2023Board 2024Board 2026Sample 2023Sample 2024Sample 2025Sample 20266 marks
From the following Balance Sheet of Raj Ltd. and the additional information given below, you are required to prepare a Cash Flow Statement (as per AS 3) for the year 2024-25.
Balance Sheet of Raj Ltd. as at 31st March, 2025 and 31st March, 2024
Particulars | Note | 31.3.2025 (₹) | 31.3.2024 (₹)
I Equity and Liabilities
1. Shareholders' Funds (a) Equity Share Capital | | 4,35,000 | 3,28,000
(b) Reserve and Surplus | 1 | 1,20,000 | 80,000
2. Non-Current Liabilities: Long-term borrowings (7% Debentures) | | 5,00,000 | 4,00,000
3. Current Liabilities: Short-term Provision (Provision for Tax) | | 15,000 | 10,000
Total | | 10,70,000 | 8,18,000
II Assets
1. Non-Current Assets: Property, Plant & Equipment (Plant & Machinery) | | 6,00,000 | 3,80,000
2. Current Assets (a) Short-term Investments | | 3,00,000 | 2,20,000
(b) Inventories | | 80,000 | 1,00,000
(c) Cash & Bank Balances (Cash at Bank) | | 90,000 | 1,18,000
Total | | 10,70,000 | 8,18,000
Notes to Accounts:
1. Reserve and Surplus: Balance in Statement of Profit & Loss 1,05,000 (2024: 70,000); Securities Premium 15,000 (2024: 10,000); Total 1,20,000 (2024: 80,000)
Additional information: During the financial year 2024-25, the company:
• Issued additional Debentures on 1st April, 2024 at a premium of 5%.
• Sold Plant & Machinery at a loss of ₹20,000, the book value of which was ₹80,000.
• Purchased additional Plant & Machinery for ₹3,50,000.
62. Calculate cash flow from operating activities (with adjustments)
4×Board 2025Board 2026Sample 2025Sample 20266 marks
(A) From the following information of HM Ltd., you are required to calculate Cash flow from Operating Activities for the year 2024-25. [3½]
Particulars | ₹
Profits for the year 2024-25, after considering the following items: | 2,42,000
• Tax provided | 40,000
• Depreciation on Office Equipment | 48,000
• Profit on Sale of Land | 26,000
• Interest on Bank Loan | 24,000
• Interim dividend | 36,000
Additional information:
• Balance of Provision for Tax on 31st March, 2025 was ₹45,000 which was increased by ₹5,000 as compared to previous year.
• Trade Receivables were increased by ₹11,000 as compared to previous year.
(B) From the following extract of the Balance Sheet of KK Ltd. and the additional information, you are required to calculate Cash and Bank Balance as at 31st March, 2025. [2½]
Particulars | 31st March, 2025 (₹) | 31st March, 2024 (₹)
Non-Current Investments | 4,00,000 | 6,00,000
Cash and Bank Balance | ? | 1,48,000
Additional information: During the year 2024-25:
• Cash flow from Operating Activities was ₹1,02,000
• Cash used in Financing Activities was ₹52,000
• Interest received on Non-Current Investments was ₹45,000
63. Calculate investing / financing cash flows from extracts
3×Board 2024Sample 2023Sample 20246 marks
Based on the following information of Neon Ltd., answer the questions given below in relation to the Cash Flow Statement of the company for the year 2022-23.
Particulars | 31.3.2023 (₹) | 31.3.2022 (₹)
Provision for Tax | 80,000 | 50,000
7% Debentures | 8,00,000 | 3,00,000
Unclaimed Dividend | 6,000 | —
Plant & Machinery (at book value) | 1,00,000 | 1,00,000
Land | 4,50,000 | 6,00,000
Note: Dividend proposed in the years 2021-22 and 2022-23 were ₹30,000 and ₹40,000 respectively.
Additional information: During the year 2022-23, the company:
(a) Provided ₹75,000 for tax.
(b) Issued 7% Debentures at a discount of 5%.
(c) Purchased Plant & Machinery for ₹40,000.
(i) What is the amount of tax paid by the company? [1]
(ii) Give the reason for the opening book value and closing book value of Plant & Machinery remaining the same, despite the purchase of a machine during the year. [1]
(iii) What is the inflow of cash from the issue of 7% Debentures? [1]
(iv) Give the company's outflow of cash for dividend paid to the shareholders. [1]
(v) State with reason whether Neon Ltd. will consider the decrease in the amount of land as an Operating Activity or as an Investing Activity, while preparing its Cash Flow Statement. [2]
64. Non-cash / non-operating adjustments to net profit (1 mark)
3×Board 2023Board 2025Sample 20241 marks
While preparing the Cash Flow Statement, the accountant of Red Hill Co. Ltd. was undecided about the impact of amortisation of discount on issue of debentures of ₹10,000 on the company's Net Operating Profit before working capital changes.
What should the accountant do to resolve this issue? Give a reason for your answer.
65. Cash and cash equivalents (1 mark)
2×Sample 2023Sample 20261 marks
Given below is an extract of the Cash flow statement of ILO Ltd.
Particulars | 31.3.2025 (₹) | 31.3.2024 (₹)
Net increase/decrease in cash & cash equivalent | (13) | 23
Opening cash and cash equivalent | 17612 | ?
Closing cash & cash equivalent | ? | 17612
You are required to find out the missing information represented by '?'.
66. Prepare Cash Flow Statement from listed information
2×Board 2023Board 20256 marks
From the following information of Realty Ltd., you are required to calculate the company's Cash and Cash Equivalent as on 31st March, 2024, by preparing a Cash Flow Statement (as per AS 3).
Information pertaining to the year 2023-24:
(i) Net profit before tax was ₹14,00,000.
(ii) Tax of ₹5,00,000 was paid.
(iii) The opening inventory was higher than the closing inventory by ₹50,000.
(iv) The Trade Creditors showed a decrease of ₹20,000 on 31st March, 2024, when compared to the amount of Trade Creditors on 31st March, 2023.
(v) Plant & Machinery on 31st March 2023, and 31st March 2024, amounted to ₹20,00,000 and ₹26,00,000 respectively.
(vi) New machinery was purchased for ₹9,00,000; the purchase consideration being 4% Debentures of the face value of ₹100 each issued at a discount of 10%.
(vii) The 4% Debentures on 31st March 2023, and 31st March 2024, amounted to ₹5,00,000 and ₹20,00,000 respectively.
(viii) ₹60,000 was paid by the company for interest on debentures against the amount due of ₹80,000.
(ix) Investments of ₹5,00,000 were purchased on 30th November, 2023, on which interest of ₹40,000 was earned and received.
(x) The cash and cash equivalent as on 31st March, 2023, was ₹3,15,000.
Ratio Analysis
67. State effect of a transaction on a ratio
8×Board 2024Board 2025Board 2026Sample 2025Sample 20261/2 marks
Debt Equity Ratio of JP Ltd. is 1.8:1.
Mention whether this ratio will improve / reduce / not change after issue of 5,000, 6% Debentures of ₹100 each.
68. Inventory turnover ratio problems (find ITR, inventory, cost or gross profit)
6×Board 2023Board 2025Board 2026Sample 2024Sample 2025Sample 20262 marks
Calculate the value of Closing Inventory of Lily Ltd. from the particulars given below:
Particulars |
Revenue from Operations | ₹5,50,000
Opening Inventory | ₹1,00,000
Inventory Turnover Ratio | 4 times
Gross Profit | 20% of Revenue from Operations
69. Operating ratio calculation
3×Sample 2023Sample 2025Sample 20261/2 marks
Calculate the operating ratio from the information given below.
Particulars | ₹
Opening Inventory | 20,000
Closing inventory | 9,000
Purchases | 80,000
Wages | 8,000
Carriage inward | 3,000
Depreciation | 18,000
Amortization | 6,000
Gross Profit | 48,000
70. Current / quick ratio calculation
4×Board 2023Board 2024Board 2026Sample 20242 marks
Calculate the Quick Ratio (up to two decimal places) of TXT Ltd. from the particulars given below:
Particulars | ₹
Working Capital | 80,000
Current Liabilities | 50,000
Note: Current Assets include Inventory of ₹20,000.
71. Profitability ratio calculation (GP, NP, operating profit ratio)
3×Board 2026Sample 20242 marks
Bloom Hotels posts ₹357 crore revenue in FY25. Bloom's EBIDTA (Earnings Before Interest, Taxes, Depreciation and Amortization) stood at ₹75.01 crore and its Profit After Tax (PAT) was ₹15.20 crore in FY25. (Source: www.ptinews.com)
Calculate the Net Profit Ratio (up to two decimal places) of Bloom Hotels from the above information.
72. Revised current ratio after a transaction
3×Board 2023Sample 2024Sample 20251/2 marks
A company had Current Assets of ₹3,00,000 and Current Liabilities of ₹1,50,000, having a current Ratio of 2:1.
What will be its revised Current Ratio after it endorses a bills receivable of ₹40,000 to one of its creditors?
73. Interpret a liquidity / solvency ratio (1 mark)
3×Board 2023Board 2024Sample 20261 marks
"The current ratio estimates a firm's capacity of paying short-term or current liabilities, including payables and debts, with its short-term or current assets. A current ratio less than 1.00 implies that the business's debts due within 12 months are more significant than its assets. Conversely, a ratio greater than 1.00 indicates that the company has sufficient assets to cover its short-term obligations." (Source: Economic Times, May 16, 2025)
Based on the above extract, explain why a very high current ratio might not always indicate an optimal financial health.
74. EPS / ROI / preference dividend calculation
3×Board 2024Board 20252 marks
Calculate the Earning per share of Hemisphere Ltd. from the particulars given below:
Particulars | ₹
10% Debentures | 5,00,000
8% Bank Loan | 3,00,000
5% Preference Share Capital | 2,00,000
Profit before Interest and Tax | 2,44,000
Provision for Tax | 20,000
Tax paid | 18,000
Equity Share Capital (@ ₹10 each) | 8,00,000
75. Interest coverage ratio calculation
2×Board 2026Sample 20252 marks
Calculate the Interest Coverage Ratio (up to two decimal places) of BT Ltd. from the particulars given below:
Particulars | ₹
8% Debentures | 10,00,000
6% Bank Loan (Long-term) | 1,50,000
Profit before Tax | 5,34,000
76. Receivables / payables / working capital turnover ratio
3×Board 2023Board 2024Board 20252 marks
Calculate the Trade Receivables Turnover Ratio of Planet Ltd. from the particulars given below:
Particulars | ₹
Revenue from Operations | 3,60,000
Cash Revenue from Operations | 90,000
Net Closing Trade Receivables | 45,000
Provision for Doubtful Debts | 10,000
77. Interest coverage ratio formula / debt protection metric (1 mark)
2×Board 2025Sample 20251 marks
According to the ratings agency, Crisil, the food and grocery players will cap their debt raising in FY 25 in order to ensure that one of the key debt protection metrics, the interest cover, remains healthy in line with the previous fiscal's level of 13 times. (Source (edited): Financial Express, 23 December, 2023)
You are required to give the formula to calculate the interest cover.
78. Debt-equity / debt to total assets ratio
2×Board 2023Sample 20262 marks
Calculate the Debt to Equity ratio from the given information:
Particulars | ₹
Current Liabilities | 3,50,000
Working Capital | 2,00,000
Non-current Assets | 8,00,000
Shareholders' funds | 6,00,000
79. Classification and objective of ratios (1 mark)
2×Board 2026Sample 20231 marks
Which one of the following ratios is NOT a part of Solvency Ratio?
(a) Debt-Equity Ratio
(b) Earnings Per Share
(c) Interest Coverage Ratio
(d) Debt to Total Assets Ratio
Accounting Application of Electronic Spreadsheet
80. Spreadsheet case: write formulas for missing cells
8×Board 2023Board 2024Board 2025Board 2026Sample 2023Sample 2024Sample 2025Sample 20266 marks
The IT Department in a school prepared the following data that showed the marks obtained by students in three subjects (out of 100).
Row | B: Roll No. | C: Mathematics | D: Computer Science | E: English | F: Total
2 | 101 | 88 | 75 | 92 | ??
3 | 102 | 65 | 80 | 70 | 215
4 | 103 | 78 | 82 | ?? | 240
5 | 104 | 90 | ?? | 84 | 256
6 | 105 | ?? | 64 | 73 | 222
Based on the above data, answer any three of the following questions:
(i) Write the formula to calculate the total marks of the student with Roll No. 101 in cell F2. [2]
(ii) Write the formula to find the marks of the student with Roll No. 103 in cell E4 in the subject English. [2]
(iii) Mention the formula to calculate the marks obtained by the student with Roll No. 104 in the subject Computer Science in cell D5. [2]
(iv) State the formula to calculate the marks of the student with Roll No. 105 in the subject Mathematics in cell C6. [2]
81. Basic spreadsheet terms (cell, range, workbook)
6×Board 2024Board 2025Board 2026Sample 2024Sample 20261/2 marks
What is meant by a cell in MS Excel?
82. Excel keyboard shortcuts
5×Board 2024Board 2026Sample 2025Sample 20261 marks
Mention the shortcut key to copy a selected cell.
83. Use of Excel functions (COUNT, MODE)
4×Board 2023Sample 20241 marks
Which formula will capture the correct number of numerical values from the following range?
A2:A5 & C2:C5
84. Sort, filter and charts in spreadsheets
3×Sample 2023Sample 20261/2 marks
What is the use of 'Sort' and 'Filter' option in accounting spreadsheets?
85. Absolute / relative cell reference (1 mark)
3×Board 2023Sample 2024Sample 20251 marks
Mention the symbol which specifies the fixed columns or rows in a formula.
86. Generic vs specific software
2×Sample 2023Sample 20242 marks
Give any two differences between Generic Software and Specific Software.
87. Arguments of the PMT function
2×Sample 2023Sample 20242 marks
The syntax of the PMT function is = PMT (rate, nper, pv, [fv], [type])
What do the following stand for in this syntax:
• Rate
• Nper
• Pv
• Type
Database Management System
88. Define basic DBMS terms
4×Board 2025Board 2026Sample 2025Sample 20261/2 marks
What is data abstraction in DBMS?
89. Entity, attribute and data types
3×Board 2025Sample 20261/2/3 marks
(i) List any three data types used in SQL.
(ii) Define Composite Attribute with suitable examples.
90. Meaning of database design
3×Board 2025Sample 2023Sample 20242/3 marks
(i) Give the meaning of Database design.
(ii) What does the PMT function calculate?
91. Primary key / keys in a table
2×Sample 2023Sample 20261 marks
Which one of the following keys is used to uniquely identify a record in a table?
(a) Foreign Key
(b) Primary Key
(c) Composite Key
(d) Alternate Key
92. Desktop vs server database
2×Board 2024Sample 20262 marks
Differentiate between Desktop Database and Server Database.
93. Storage devices / storage manager in DBMS
2×Board 2025Sample 20252 marks
List the components of storage manager.
94. Integrity rules and keys (foreign key, referential integrity)
2×Board 2023Sample 20262 marks
Why is a Foreign Key used in a database?
95. Basic SQL commands
2×Board 2024Sample 20252 marks
What are the SQL statements used in Database testing to manipulate the test table?
96. Database transaction with example
2×Sample 2023Sample 20243 marks
(i) What is a Database Transaction in DBMS?
(ii) Give an example of a Database transaction.
97. Attributes stored in a payroll database
2×Sample 2023Sample 20242 marks
List any two attributes to be stored in Payroll Data base.
98. Term not related to computerised databases (1 mark)
2×Board 2023Sample 20241 marks
Which one of the following terms is NOT related to computerised databases?
(a) Search
(b) Sort
(c) Field names
(d) Record grab